Lawyer Profile
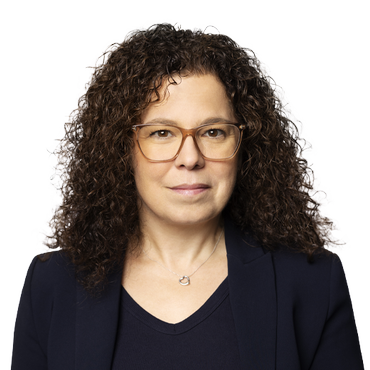
Josianne Beaudry
Montréal, Québec
Overview
The federal budget presented on November 4, 2025 (the “Budget”), proposes a significant change to the Critical Mineral Exploration Tax Credit (CMETC). As a reminder, the CMETC is equal to 30% of “specified mineral exploration expenses”1 incurred in Canada that a company has renounced to flow-through share investors. Critical minerals currently eligible for the CMETC The critical minerals currently eligible for the CMETC are nickel, cobalt, graphite, copper, rare earth elements, vanadium, tellurium, gallium, scandium, titanium, magnesium, zinc, platinum group metals, uranium and lithium (including lithium from brine deposits). Critical minerals added to the list The Budget proposes to expand the definition of “critical mineral” to include the following additional critical minerals: bismuth, cesium, chromium, fluorspar, germanium, indium, manganese, molybdenum, niobium, tantalum, tin and tungsten. Impact of this measure on mining exploration expenses The measure will make the 30% CMETC apply to exploration expenses relating to these new types of critical minerals that a mining exploration company would renounce to flow-through share investors. The measure will cover exploration expenses renounced under flow-through share agreements entered into after Budget Day and on or before March 31, 2027. The Budget also confirms the renewal of the Mineral Exploration Tax Credit until March 31, 2027 (METC). Please feel free to contact our professionals for more information Canadian exploration expenses incurred by a company after April 7, 2022, as part of mineral exploration activities conducted from or above the surface of the earth targeting mainly critical minerals.
On March 25 last, the Quebec Minister of Finance unveiled his 2025-2026 budget, which significantly transforms the tax landscape of the mining sector in Quebec. This budget introduces major changes to the flow-through share regime and to the tax credit relating to resources, which will have significant implications for investors and businesses in the natural resources sector. Changes to the flow-through share regime Abolition of both 10% additional deductions As part of the review of its tax expenditures, the government has decided to adjust the flow-through share regime. As a result, the following deductions have been abolished: the additional 10% deduction for certain exploration expenses incurred in Quebec by a mining corporation that does not exploit any mineral resources; the additional 10% deduction for certain surface mining exploration expenses incurred in Quebec by a mining corporation that does not exploit any mineral resources. With some exceptions1, these changes will apply to flow-through shares issued after March 25, 2025. It should also be noted that the budget abolishes the additional capital gains exemption resulting from the divestiture of certain resource-related properties, such as flow-through shares. On the other hand, the additional deduction for certain issuance costs seems to be maintained. Changes to the tax credit relating to resources Despite these abolitions, the budget does include some positive news for the critical and strategic metals sector. The budget provides for a temporary increase in the rates of the tax credit relating to resources for eligible expenses related to critical and strategic minerals. Until December 31, 2029, a 45% tax credit rate will apply to these costs for eligible corporations, that is, those that do not exploit any mineral resources, and 20% for other eligible corporations, that is, those that exploit mineral resources. For the purposes of the tax credit relating to resources, critical minerals will refer to the following minerals: antimony, bismuth, cadmium, cesium, copper, tin, gallium, indium, tellurium and zinc. Strategic minerals are defined as cobalt, rare earth elements, platinum group elements, graphite (natural), lithium, magnesium, nickel, niobium, scandium, tantalum, titanium and vanadium. Several other technical changes have also been made to the tax credit relating to resources. These will be the subject of a more detailed bulletin at a later date. The changes introduced by the 2025-2026 Quebec budget will certainly have an impact on the tax planning of enterprises and investors in the natural resources sector. Our team of mining law and tax professionals is ready to answer all your questions regarding these new measures. We can assist you in developing your mining investment projects in Quebec, maximizing the benefits of the enhanced rates of the tax credit relating to resources, as well as in implementing successful flow-through financing. These amendments will not apply to shares issued after March 25, 2025, but before January 1, 2026, provided that they are issued following an application for a preliminary prospectus receipt made no later than March 25, 2025. Nor will they apply to shares issued after March 25, 2025, if issued following a public announcement made no later than March 25, 2025, and if the report of distribution form is submitted to the Autorité des marchés financiers no later than May 31, 2025.
On March 3rd, 2025, the Department of Finance Canada announced a two-year extension to the 15% Mineral Exploration Tax Credit (“METC”) available to investors in flow-through shares. The extension means that the METC will be effective until March 31, 2027. This announcement came at a time when uncertainty loomed over the industry and some stakeholders feared that the government would not renew the METC. Over time, this tax credit has become a key component of flow-through share financings. It is intended to enhance the tax deductions already available to flow-through share holders and ultimately help companies raise capital for mineral exploration. The METC was last renewed in 2019 for a five-year period, indicating the government’s long-term commitment to the sector at that time. And while this renewal is welcome news for exploration companies, it should be noted that the shorter two-year horizon of the extension does not provide the same assurance regarding the incentive’s future. It is possible that this two-year renewal reflects the government’s intention to promote the new 30% Critical Mineral Exploration Tax Credit (“CMETC”) instead, on which more information can be found here: Federal Budget 2022: Good News for Mining Exploration Companies! In closing, it is important to note that the one-year extension to the 15% METC will not affect the period during which the 30% CMETC is available for critical mineral exploration, which will end on March 31, 2027, and is subject to renewal. If you were planning on financing non-critical mineral exploration, you may want to complete this transaction within the next two years in order to benefit from the 15% METC. Our team of professionals specializing in securities, mining law and taxation is available to answer any questions you may have concerning this new measure and to guide you in arranging a successful flow-through financing.
On March 28, 2024, the Department of Finance Canada announced a one-year extension to the 15% Mineral Exploration Tax Credit (“METC”) available to investors in flow-through shares. The extension means that the METC will be effective until March 31, 2025. This announcement came at a time when uncertainty loomed over the industry and some stakeholders feared that the government would not renew the METC. Over time, this tax credit has become a key component of flow-through share financings. It is intended to enhance the tax deductions already available to flow-through share holders and ultimately help companies raise capital for mineral exploration. The METC was last renewed in 2019 for a five-year period, indicating the government’s long-term commitment to the sector at that time. And while this renewal is welcome news for exploration companies, it should be noted that the shorter one-year horizon of the extension does not provide the same assurance regarding the incentive’s future. It is possible that this one-year renewal reflects the government’s intention to promote the new 30% Critical Mineral Exploration Tax Credit (“CMETC”) instead, on which more information can be found here: Federal Budget 2022: Good News for Mining Exploration Companies! In closing, it is important to note that the one-year extension to the 15% METC will not affect the period during which the 30% CMETC is available for critical mineral exploration, which will end on March 31, 2027, and is subject to renewal. If you were planning on financing non-critical mineral exploration, you may want to complete this transaction in the coming year in order to benefit from the 15% METC. Our team of professionals specializing in securities, mining law and taxation is available to answer any questions you may have concerning this new measure and to guide you in arranging a successful flow-through financing.
Lavery is proud to announce that 42 partners are ranked among the leading practitioners in Canada in their respective practice areas in the 2026 edition of The Canadian Legal Lexpert Directory. The following Lavery partners are listed in the 2026 edition of The Canadian Legal Lexpert Directory: Asset Securitization Brigitte M. Gauthier Banking Étienne Brassard Class Actions Laurence Bich-Carrière Myriam Brixi Marie-Nancy Paquet Construction Law Laurence Bich-Carrière Nicolas Gagnon Marc-André Landry Ouassim Tadlaoui Corporate Commercial Law Étienne Brassard Jean-Sébastien Desroches Christian Dumoulin Alexandre Hébert Édith Jacques Paul Martel André Vautour Corporate Finance & Securities Josianne Beaudry René Branchaud Corporate Mid-Market Étienne Brassard Jean-Sébastien Desroches Alexandre Hébert Édith Jacques André Vautour Employment Law Benoit Brouillette Frédéric Desmarais Simon Gagné Richard Gaudreault Marie-Josée Hétu Guy Lavoie Josiane L’Heureux Zeïneb Mellouli Environment Valérie Belle-Isle Family Law Caroline Harnois Awatif Lakhdar Elisabeth Pinard Infrastructure Law Nicolas Gagnon Insolvency & Financial Restructuring Yanick Vlasak Insolvency Litigation Jean Legault Ouassim Tadlaoui Yanick Vlasak Jonathan Warin Intellectual Property Chantal Desjardins Alain Y. Dussault Isabelle Jomphe Eric Lavallée Labour (Management) Benoit Brouillette Brittany Carson Simon Gagné Richard Gaudreault Marie-Josée Hétu Marie-Hélène Jolicoeur Guy Lavoie Carl Lessard Zeïneb Mellouli Litigation - Commercial Insurance Dominic Boisvert Martin Pichette Litigation - Corporate Commercial Laurence Bich-Carrière Marc-André Landry Litigation - Product Liability Laurence Bich-Carrière Myriam Brixi Medical Negligence Anne Bélanger Mergers & Acquisitions Josianne Beaudry Étienne Brassard Jean-Sébastien Desroches Christian Dumoulin Alexandre Hébert Édith Jacques Mining Josianne Beaudry René Branchaud Occupational Health & Safety Josiane L'Heureux Professional Liability Marie-Nancy Paquet Judith Rochette Technology André Vautour Workers' Compensation Marie-Josée Hétu Josiane L'Heureux Guy Lavoie Carl Lessard
On September 3rd, 2025, Lexpert recognized the expertise of three of our partners in The Lexpert Special Edition: Mining 2025. Josianne Beaudry, René Branchaud and Sébastien Vézina are recognized among Canada’s leaders, highlighting the firm’s excellence and strategic role in Mining law. Josianne Beaudry is a partner and leader of the Business law group at Lavery. Her practice is primarily focused on securities law. She advises financial sector participants on the application of regulations relating to securities and corporate governance. René Branchaud practises in the fields of securities, mergers and acquisitions, as well as corporate law. With more than thirty years’ experience, he advises companies on matters such as incorporation and organization, the drafting of shareholder agreements, private placements, public issues, going public, dispositions, and takeovers. Sébastien Vézina is a partner in the firm’s Business Law group. Over the years, he has refined his practice and developed a particular interest in negotiating commercial agreements with companies in the mining and renewable energy sources, financial services and sports and entertainment industries. Generally, Sébastien's practice in these different industries includes public and private mergers and acquisitions, public and private financing, private sector investments and company buyouts, in particular cross-border transactions between Canada and the United States and international transactions, and the negotiation of various commercial agreements. About Lavery Lavery is the leading independent law firm in Quebec. Its more than 200 professionals, based in Montréal, Québec City, Sherbrooke and Trois-Rivières, work every day to offer a full range of legal services to organizations doing business in Quebec. Recognized by the most prestigious legal directories, Lavery professionals are at the heart of what is happening in the business world and are actively involved in their communities. The firm’s expertise is frequently sought after by numerous national and international partners to provide support in cases under Quebec jurisdiction.
On April 16, 2025, Lexpert recognized the expertise of seven of our partners in its 2025 Lexpert Special Edition: Finance and M&A. Josianne Beaudry now ranks among Canada’s leaders in the area of finance and Étienne Brassard, Jean-Sébastien Desroches, Édith Jacques, Paul Martel and André Vautour are among Canada’s leading lawyers in mergers and acquisitions. Finance Josianne Beaudry is a partner and a member of the firm’s Business Law group. Josianne is primarily focused on securities law, investment funds and mining law. She also advises financial sector participants on the application of regulations relating to securities and corporate governance. Mergers and Acquisitions Étienne Brassard practises business law, more specifically corporate financing, mergers and acquisitions and corporate law. He advises local and international businesses in relation to all forms of private financing, from traditional or convertible debt to equity investments. Jean-Sébastien Desroches practises business law and focuses primarily on mergers and acquisitions, infrastructure, renewable energy and project development as well as strategic partnerships. Édith Jacques is a partner in our Business Law Group in Montréal. She specializes in mergers and acquisitions, commercial law and international law. Édith acts as strategic business advisor for medium to large private companies. Paul Martel is a partner in the Business Law Group. He practises primarily in the area of corporate law, focusing on corporations, not-for-profit corporations and general partnerships. He is also an expert in commercial contracts. Paul is recognized for his ability to find effective, innovative solutions to the most complex legal issues in corporate law. André Vautour practises corporate law and commercial law, and is specifically interested in corporate governance, strategic alliances, joint ventures, investment funds, and mergers and acquisitions of private companies. About Lavery Lavery is the leading independent law firm in Quebec. Its more than 200 professionals, based in Montréal, Québec City, Sherbrooke and Trois-Rivières, work every day to offer a full range of legal services to organizations doing business in Quebec. Recognized by the most prestigious legal directories, Lavery professionals are at the heart of what is happening in the business world and are actively involved in their communities. The firm’s expertise is frequently sought after by numerous national and international partners to provide support in cases under Quebec jurisdiction.
Practice Areas
Bar Information
Called to the bar: 2000 (QC)